Quick Answer
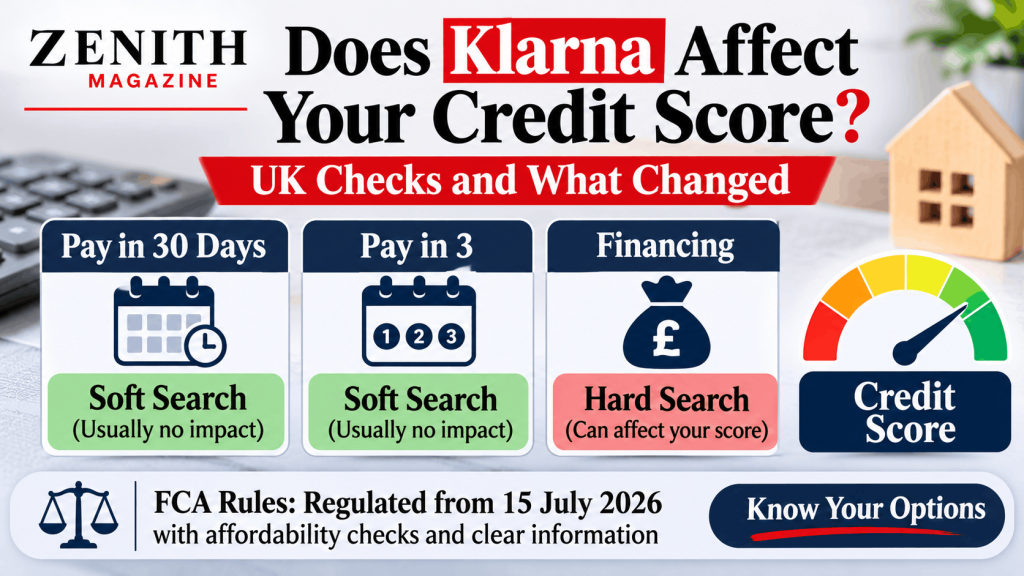
Does Klarna affect credit score? It can. Checkmyfile (updated 9 June 2026) says Klarna’s interest-free options use a soft search, which does not affect your score, while Klarna financing uses a hard check, which can. Klarna has reported late and unpaid payments to credit reference agencies since June 2022, so future lenders can see them. This is general information, not personal advice.
Key Takeaways
- The product matters. Pay in 30 days and Pay in 3 are described as soft search products, and financing as a hard search product, by one UK credit-file provider. Klarna’s own current wording could not be opened for this article.
- Missed payments are the part most likely to cause lasting harm. Sources say late or unpaid payments can be reported, and Checkmyfile says they stay on a file for six years.
- UK regulation changed on 15 July 2026, but the official pages we read describe affordability checks, information and complaints, not new credit file rules.
Buy now, pay later (BNPL) looks like a way to avoid credit, but the line has been blurring since 2022. This article sets out what the UK sources say, with dates, and where they run out. All facts were checked on 31 October 2026, and the rules and Klarna’s products may have changed by the time you read this.
How Klarna works
Klarna offers several ways to pay in the UK, and the credit file effects depend on which one you use. Checkmyfile (published 6 February 2025, updated 9 June 2026) describes them this way:
| Klarna option | What it is | Search type according to Checkmyfile |
| Pay in 30 days | You get the item first and pay within 30 days | Soft search |
| Pay in 3 instalments | Three equal interest-free payments, taken monthly, first at checkout | Soft search |
| Financing | Loan-style repayment over 6 to 36 months, with interest | Hard search |
Checkmyfile is a credit-reporting service, not Klarna. We could not open Klarna’s own UK pages for this article, so treat the table as a secondary source and check Klarna’s current terms.
Credit checks: what Klarna searches and reports
A credit search is when a company looks at your credit file. A soft search is visible to you but, according to Experian, does not affect your score. A hard search can affect it.
Does Klarna run a soft credit check?
For the interest-free options, yes according to Checkmyfile: applying to pay with Klarna usually triggers a soft search. Experian’s consumer guidance (the page shows data from June 2026 and no publication date) says soft checks “don’t affect your score” and are more common among BNPL firms, while some firms may carry out a hard check.
Klarna soft search showing on Experian credit report
Seeing a Klarna entry on your Experian report does not mean your score has dropped. Checkmyfile says soft searches from Klarna show on your credit report but do not affect your score. We found no source that explains which organisations can see soft searches, so we are not making a claim about that.
Does Klarna financing do a hard credit check?
Yes, according to Checkmyfile, which says financing triggers a hard search that appears on your credit report and could influence your score. Klarna financing is a longer, interest-bearing loan, so this is closer to how other loans work. Always read the terms before agreeing.
Does Klarna pay in 3 affect credit score?
Pay in 3 uses a soft search, per Checkmyfile, so the application itself should not move your score. The payments are a separate matter. Klarna said in 2022 that it would report Pay in 3 and Pay in 30 orders made on or after 1 June 2022 to Experian and TransUnion, covering on-time payments, late payments and unpaid purchases (LBC and Which?, 4 May 2022). Which? added at that time that “your overall credit score won’t be impacted for now”, because the credit reference agencies needed to update their scoring first, and said Experian expected 12 to 18 months for this. That was a 2022 position. Experian’s current consumer page says BNPL can affect your score depending on the lender and whether it reports, but it does not say how Klarna is treated today.
Does Klarna pay in 30 days affect credit score?
The same picture applies. Pay in 30 days uses a soft search per Checkmyfile, and the 2022 reporting covered Pay in 30 orders too. If you pay on time, the sources suggest it may show as a repayment on your file. If you pay late, it can be recorded and seen by future lenders, as Experian puts it.
Does downloading the Klarna app affect credit score?
We found no source that tests this. Checkmyfile ties the soft search to applying to pay with Klarna, not to downloading or opening an app. Our reading, which is reasoning and not a sourced fact, is that installing the app on its own is not an application. If you see a search on your report that you do not recognise, ask Klarna what it relates to.
Does Klarna account balance count towards credit utilization?
Probably not in the way a credit card does, though we found no source that says so directly. Experian defines the credit utilisation ratio as the percentage of your available credit that you are using, and says it applies to revolving credit such as credit cards and overdrafts, while loans and mortgages do not count. Experian’s page does not mention BNPL. Our reasoning is that Pay in 3 and financing are fixed repayments, not a limit you can keep reusing, but this is an interpretation. Check your own report to see how a Klarna agreement is shown.
Missed payments
Klarna automatic payment failed does it affect credit?
A failed payment can lead to a late payment, and late payments can be reported. Checkmyfile says late or missed payments are reported to the credit reference agency and stay on your credit file for six years, and that missing many consecutive payments, often around six months, can lead Klarna to start default proceedings. Which? reported in 2022 that late and outstanding payments would be reported. We could not find a source that says how quickly a failed automatic payment is reported after the due date, so contact Klarna at once if a payment fails.
Late fees are a separate cost. Which? reported on 28 February 2023 that Klarna would charge £5, or 25% of the order value for orders under £20, with a maximum of two late fees per order and a seven-day grace period, for orders from 16 March 2023. That is a 2023 report, so check Klarna’s current terms.
How to remove Klarna late payment from credit history
We found no official route for removing an accurate late payment early. The sources describe a retention period (Checkmyfile says six years) and a route for errors. Which? (24 October 2022) says errors should be reported to the credit reference agency, which adds a notice of dispute and must respond within a month. If the lender does not agree to correct it, you can add a notice of correction explaining the error. In the Which? case a Klarna financing mark was removed after the customer complained, with Klarna saying its direct debit setup was misleading at the time. That does not show that accurate marks can be removed.
Returns, refunds and disputes
Will Klarna refund affect my credit file?
We found no source that answers this directly. Our reasoning is that a refund changes the amount you owe, so the sensible step is to check that Klarna has updated your balance and that your credit file shows the right position afterwards. If a mark looks wrong, use the dispute route described above.
Does disputing a Klarna return affect credit rating?
Again, no source we opened covers this. The risk we can identify is that a payment you believe is not due is shown as late. If that happens, tell Klarna in writing, and consider a notice of dispute with the credit reference agency, as Which? describes. The FCA says you should ask your lender to put things right first and can then complain to the Financial Ombudsman Service.
Regulation: what changed on 15 July 2026
The FCA (page last updated 6 August 2026) says it started regulating Deferred Payment Credit, often called buy now pay later, on 15 July 2026. MoneyHelper (updated 16 July 2026) says third-party BNPL products from providers including Klarna are regulated if taken out on or after that date.
According to the FCA and MoneyHelper, regulated lenders must:
- check you can afford to repay before you take out an agreement
- give you key information first, including repayment dates and amounts, late fees, and your rights
- contact you after a missed repayment and offer support if you are struggling
You can complain to the lender and then to the Financial Ombudsman Service. The FCA also says Section 75 of the Consumer Credit Act may let you get a refund from the lender.
There are limits. Agreements taken out before 15 July 2026 remain unregulated, and so do deals where the lender and the seller are the same business (FCA). Neither the FCA nor MoneyHelper page says anything about changes to credit files or credit scoring, so the regulation does not on its face change how Klarna reports.
Using it sensibly
This is general guidance, not personal financial advice.
- Check which Klarna option you are choosing. Financing is closer to a loan than the interest-free options.
- Set up the payment reliably. A missed payment is the part sources say can be reported and seen by lenders.
- Look at your own credit reports from the credit reference agencies (Experian, Equifax and TransUnion are the three main ones). The sources we read named Experian and TransUnion as Klarna’s recipients in 2022, and did not mention Equifax.
- If you plan to apply for a mortgage or other large borrowing soon, expect lenders to see Klarna entries. The Which? mortgage case from 2022 shows how a financing mark caused a refusal until it was removed.
- If you are struggling, tell Klarna early and look at MoneyHelper’s free guidance.
Frequently Asked Questions
Can using Klarna hurt your credit file?
Yes, if payments are late or unpaid. Sources say Klarna can report late and outstanding payments and that future lenders can see them. A soft search for the interest-free options is not meant to affect your score, but financing involves a hard search that can.
Does Klarna do a hard credit check?
Not for Pay in 30 days or Pay in 3, according to Checkmyfile (updated June 2026), which describes soft searches. It says Klarna financing involves a hard check. Experian says some BNPL firms use hard checks, so check the terms before you agree.
Will a missed Klarna payment show on my credit report?
It can. Which? reported in 2022 that late and outstanding payments would be reported to Experian and TransUnion, and Checkmyfile says they stay on your file for six years. We could not confirm exactly how soon after the due date it is reported.
Can I get a Klarna late payment removed from my credit file?
Only if it is wrong, as far as the sources show. You can tell the credit reference agency to add a notice of dispute, which must be answered within a month (Which?, 2022). We found no official way to remove an accurate late payment early.
Does a Klarna refund change my credit file?
We found no source that answers this. A refund should change what you owe, so check that Klarna updates your balance and that your report reflects it. If something looks wrong, ask Klarna to correct it and use the dispute route.
Is Klarna regulated in the UK?
Third-party BNPL products from providers such as Klarna are regulated by the FCA if taken out on or after 15 July 2026 (MoneyHelper, 16 July 2026). Agreements taken out earlier remain unregulated. You can complain to the Financial Ombudsman Service if the lender does not put things right.